NSW Transport Secures $510K After Bank Rejection
Business Loans, Asset Finance, Private Lending, Case Study
Discover how Go For Broker helped a NSW transport operator secure $510,000 in funding - including a $160,000 second mortgage and a $350,000 truck refinance - after nine months of serious illness left his credit file damaged and his trucks days from repossession, and banks declined to help.
Nine months off work, trucks days from repossession, a credit file with fresh damage on it. The bank saw a risk. We saw a timing problem - and structured a facility built to disappear once the client was back on his feet.
It's the question every declined borrower asks: if the bank said no, why would anyone else say yes - and what does that cost? On the surface, this looked like a bad deal. A damaged credit file, a property mid-renovation, trucks about to be repossessed. But risk and timing aren't the same thing, and when you separate them, the picture changes.
First, Why the Banks said No
The bank wasn't wrong about what it saw - it just wasn't set up to look any further.
The credit file had fresh damage. Missed payments during nine months of serious illness had left defaults and court action on file - exactly the kind of history a bank's policy grid is built to decline, regardless of the reason behind it.
The property was mid-renovation. A property part-way through work is harder to value and harder to lend against. A bank wants a clean valuation; a partly-finished renovation isn't one.
The equity alone wasn't enough. Even with the property as security, it couldn't raise the full amount required on its own - and most private lenders approached weren't willing to look past the credit history to structure around it.
None of that means the business was unsound. It means the situation didn't fit a standard lending policy, and policy doesn't ask why.
Our Thinking
This wasn't financial recklessness - it was nine months of illness landing on an otherwise solid business. The client didn't need to be assessed as a credit risk. He needed a lender willing to structure around the timing, not around the credit file alone.
The Numbers
Here is what was actually arranged, and what it cost.
Second Mortgage: $160,000
Term: 12 Months
Working Capital Component: Capitalised interest for the first 6 months - no repayments required during that period.
Additional Facility: $350,000 truck refinance
Total Funding Arranged: $510,000
What people miss
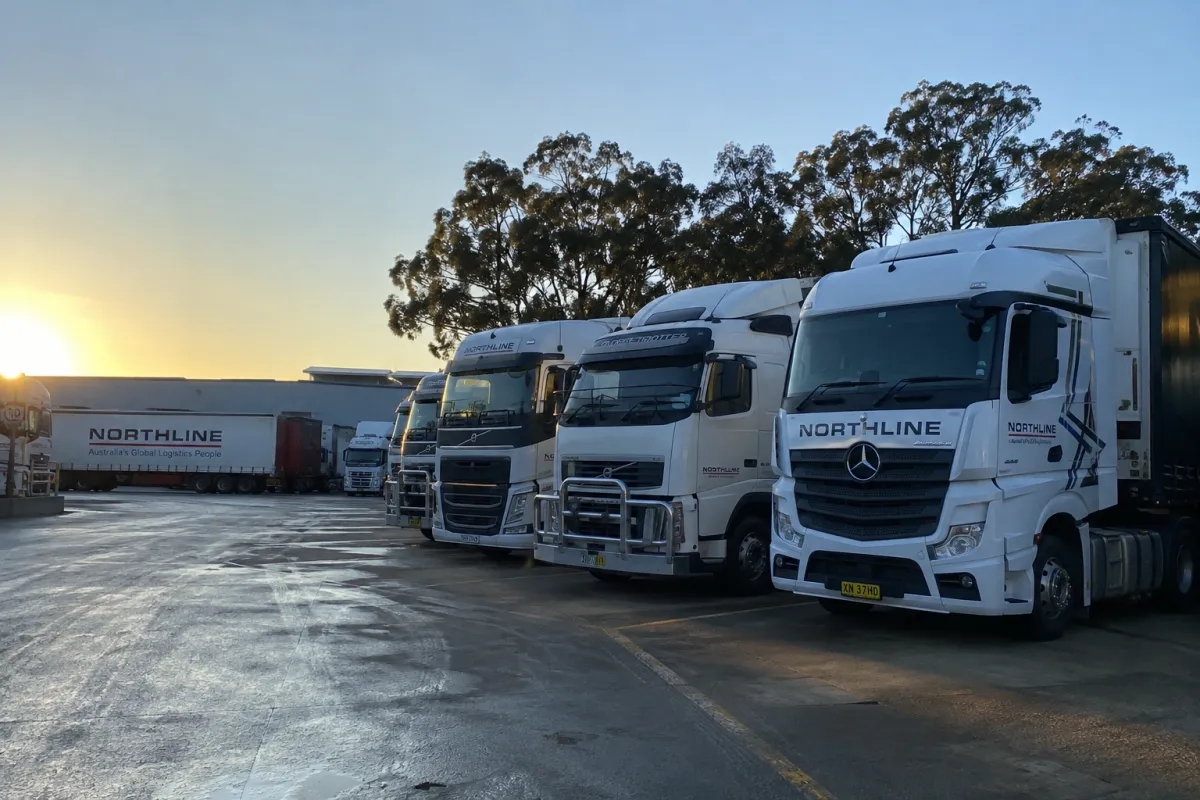
The comparison people jump to is what a private facility costs against what a bank would have charged. That's the wrong comparison, because the bank wasn't offering anything at all - it had already declined. The real comparison is the cost of this facility against the cost of doing nothing: $350,000 in trucks repossessed, the fleet off the road, and a business that stops operating the day that happens. Against that outcome, the facility isn't the expensive option - it's the only option that kept the business trading.
The point isn't that one is better
A bank loan is the right tool when a business has clean, current financials and time on its side, and it's almost always the cheaper option when it's available. But that option wasn't on the table here - not because the business was unsound, but because nine months of illness had put fresh marks on a file that a bank's process isn't built to look past.
Private lending isn't a substitute for a bank loan. It's a different tool for a specific window: get the business stable, clear the immediate risk, and refinance back to a bank once the file and the property are clean again - which is exactly the plan now in motion.
The Outcome
$350,000 of trucks refinanced, removing the immediate repossession risk
$160,000 second mortgage arranged over 12 months
Working capital component structured with 6 months of fully capitalised interest - no repayments required during that period
Defaults and court action cleared from the client's credit file
Client is now refinancing the full facility back to a mainstream bank
Could Your Clients Benefit from a Similar Strategy?
If you're an accountant, adviser, or agency working with a client whose bank has walked away over a damaged credit file, an incomplete property, or a deadline that's too tight for a standard process, this case shows what's achievable with the right structure and the right lender. For businesses and SMEs across Australia, a life event or temporary setback shouldn't have to mean losing critical assets or stalling the business entirely.
Whether the underlying pressure is a recent bank decline, a credit file carrying fresh damage from circumstances outside the client's control, or an asset facing imminent repossession, a well-structured private facility - backed by experienced brokers with genuine access to non-bank and private lending - can buy the time needed to stabilise, and a clear path back to mainstream lending once the immediate risk has passed.
FAQs
Why would a private lender charge more than a bank? The pricing reflects what the loan actually is, not just the borrower. A bank rate assumes clean financials, a straightforward valuation, and a long-term hold. A private lender pricing around fresh defaults, a mid-renovation property, and a repossession deadline is pricing for risk the bank simply declines rather than assesses - and for the speed needed to act before the trucks were gone.
Is a higher-cost private loan actually worth it? It depends what it's replacing. Measured against a bank rate that was never actually on offer, it can look expensive. Measured against $350,000 in trucks being repossessed and a business stopping overnight, it's the cost of staying operational. The cost only makes sense next to the real alternative, not an unavailable one.
Can I get a business loan if my credit file has defaults or court action listed? Yes - private lenders can often look past a damaged credit file if the underlying cause is explainable, such as illness or a temporary setback, provided there's a clear plan and adequate security, rather than declining on the credit report alone.
Can I get a loan with no repayments while I get back on my feet? Some private lenders offer facilities with capitalised interest for a defined period - six months, in this case - meaning interest is added to the loan balance rather than paid monthly, before regular terms resume.